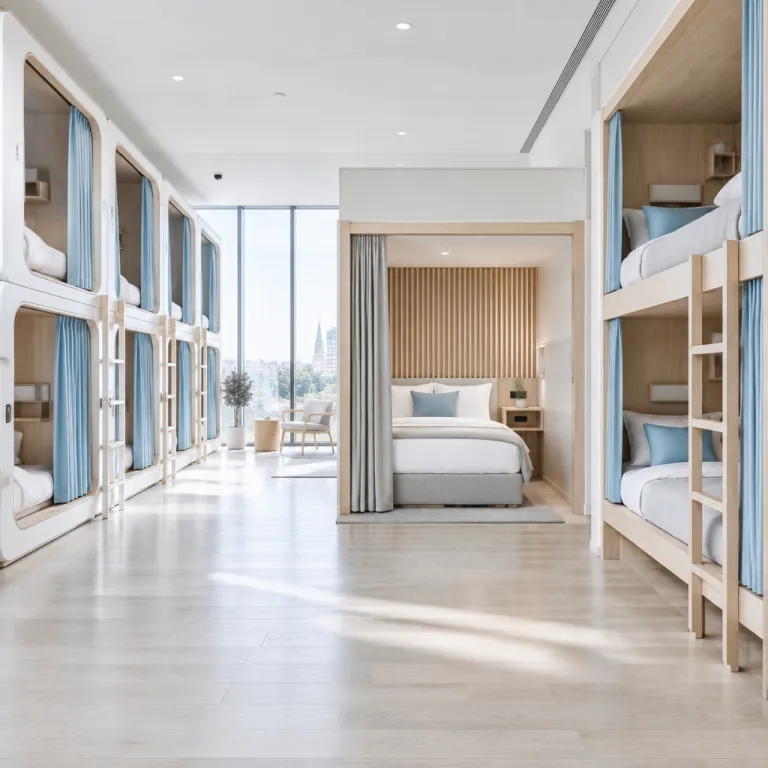
The classification problem that sits inside every capsule pod
Capsule hotel classification regulation starts with a simple architectural provocation. Most hotel market rules in each country still define a standard hotel room by minimum floor area, window requirements and private bathroom size, while a capsule hotel deliberately compresses the private space to a pod that can be under 3 square metres. For travelers used to traditional hotels in north america or the united states, that shift in room type feels radical yet strangely logical in dense city centres.
Regulators built their global market frameworks around doors, not curtains, and around rooms, not stacked capsules. When a capsule hotel opens in asia pacific or latin america, local inspectors often reach for hotel or hostel checklists that were written for corridors of full size rooms, which makes any serious analysis of capsule hotels difficult and inconsistent. That is why capsule hotel classification regulation now sits at the heart of every forecast about capsule hotels market growth, market share and long term market size.
For premium capsule hotels that target the business traveler type and higher spending solo traveler type, this grey zone is more than a legal curiosity. A luxury capsule hotel that offers concierge service, refined shared lounges and quiet pods for an older age group still gets squeezed into hostel style categories in some parts of asia or east africa, which distorts the hotels market data and confuses travelers. Serious global analysis of the capsule hotels market must therefore separate the physical capsule from the service level, the booking mode and the traveler type age profile.
From a market perspective, the classification problem also hides real value. When capsule hotels are coded as hostels in a hotel market database, their revenue per available pod, their occupancy and their share of business booking mode are misread, which underestimates the global growth of this segment. For investors tracking the global market for hotels, that misclassification can make the capsule hotel segment look like a niche, even as its market share quietly expands in asia pacific, north america and selected cities in latin america.
For travelers, the stakes are more personal than any usd forecast about market size. A capsule hotel that appears in a hostel filter on a booking platform may attract a younger age group expecting dorm style social energy, while the same property might actually be engineered for quiet business travelers who want privacy and reliable Wi Fi. That mismatch between traveler type and regulatory label is exactly why capsule hotel classification regulation must evolve beyond the old hotel versus hostel binary.
Hotel vs hostel vs new category: why the label shapes safety, zoning and tax
Once you step beyond the pod, capsule hotel classification regulation becomes a question of fire codes, evacuation routes and tax receipts. Traditional hotel rules in the united states, europe and much of asia define a hotel by room size, window access and corridor width, while hostel regulations often assume shared dormitories with fewer privacy barriers. A capsule hotel sits awkwardly between these two types, with enclosed capsules that feel like private rooms stacked inside a shared volume, which is why regulators struggle to decide whether the hotels market should treat them as hotel, hostel or a new category.
Fire safety is where this ambiguity becomes critical for every traveler. In a conventional hotel, evacuation analysis assumes one or two people per room and clear sightlines from bed to door, but a capsule hotel can host dozens of travelers in a single hall of pods, each with its own curtain or door and sometimes integrated electronics. When a capsule hotel is regulated as a hostel in one country and as a micro hotel in another, the same physical layout can be subject to different sprinkler requirements, smoke extraction rules and emergency lighting standards, which is why operators and guests both need transparent capsule hotel classification regulation.
Zoning and taxation follow the same pattern. City planners in north america or the middle east may classify a capsule hotel as a hostel to keep it out of prime business districts, while the same concept in asia pacific might be welcomed as an efficient hotel type that supports transit hubs and high speed rail stations. That patchwork echoes the Airbnb story, where a new accommodation mode forced cities to rewrite zoning codes and tax rules, and capsule hotels now face a similar global market reckoning as their market share rises in key gateway cities.
For premium capsule hotels that target business travelers extending trips into leisure, the classification label can decide whether they are allowed in central business districts at all. A property that is coded as a hostel may be blocked from certain office led zones, even if its traveler type profile is closer to an upscale business hotel than to a backpacker dorm. Anyone interested in how fire codes and zoning laws decide which cities get capsule hotels should read the detailed breakdown on capsule hotel zoning and fire regulation, which shows how capsule hotel classification regulation can either unlock or freeze market growth.
Taxation adds another layer of complexity to the global market analysis. Some countries apply hotel level occupancy taxes to capsule hotels, while others treat them like hostels or even like short term rentals, which changes the effective price per night and the perceived value for different traveler type age groups. As capsule hotels expand from asia to latin america, east africa and the middle east, the lack of a consistent tax and zoning category risks fragmenting the hotels market and obscuring the true market size of this compact yet increasingly influential format.
Consumer protection, star ratings and what quality means in a pod
For travelers, capsule hotel classification regulation is not an abstract legal debate but a question of trust. Star ratings, quality seals and guest review scores were all designed around the traditional hotel model, where room size, bathroom fittings and in room amenities define the baseline. When that model is applied to capsule hotels, a property can be penalised for the very design choices that make the capsule type efficient, sustainable and often more affordable for solo travelers and business guests.
Most hotel rating systems still assume that more square metres equal more comfort, which is not always true in a well engineered capsule hotel. A premium capsule hotel in tokyo or singapore can offer a perfectly calibrated pod with excellent ventilation, sound insulation and lighting, yet still receive a lower star rating than a larger but poorly maintained hotel room in another part of the same city. That disconnect shows why capsule hotel classification regulation must evolve to recognise pod specific quality indicators, from pod ergonomics to shared space design and digital booking mode experience.
Consumer protection agencies also face a challenge when capsule hotels are mislabelled as hostels. A traveler who books a capsule hotel expecting a quiet, semi private pod may arrive to find an open dorm with minimal separation, because the property has stretched the capsule label without meeting any clear standard. Conversely, a high end capsule hotel that invests heavily in safety, cleanliness and staff training may be lumped into a generic hostel category, which undermines its position in the hotel market and confuses travelers comparing options across the global market.
Booking platforms have started to respond by adding capsule hotel as a distinct filter, but their internal hotels market taxonomies still often map capsules back to hotel or hostel categories for reporting and usd forecast models. That means the market share of capsule hotels within the wider hotel market is still under reported, especially in asia pacific and north america where growth is fastest among younger business travelers and design conscious solo guests. For a deeper look at how pricing models intersect with capsule hotel classification regulation, the guide to hourly, nightly and monthly capsule pricing explains how booking mode and stay length influence both traveler expectations and regulatory scrutiny.
Group booking behaviour adds another twist to consumer protection. When a corporate travel manager arranges a group booking for a mixed age group of executives, they need clarity on whether the property meets hotel grade fire standards, business friendly services and privacy norms, not just hostel level basics. Capsule hotel classification regulation that clearly defines traveler type, pod density and shared facility standards would give both solo traveler and group booking segments more confidence, while also giving regulators a clearer view of the hotels market and its evolving market size.
Global regulatory models and why operators must push for a clear capsule category
Japan remains the reference point for capsule hotel classification regulation, because it treated the first capsule hotels as a legitimate hotel type rather than a novelty. Building codes, fire regulations and licensing frameworks were gradually adapted to recognise that a capsule hotel concentrates sleeping pods while relying on generous shared facilities, and that this configuration can be safe when engineered correctly. As the concept spread from asia to europe, north america, latin america, the middle east and east africa, many countries imported the aesthetic of capsules without importing the same regulatory clarity.
Europe illustrates the patchwork problem that now shapes the global market for capsule hotels. In some european cities, capsule hotels are licensed as hotels with reduced room size exemptions, while in others they are treated as hostels or even as experimental lodging that falls under temporary permits. That inconsistency makes serious analysis of the hotels market difficult, because the same capsule hotel concept can appear under different categories in national statistics, which distorts market growth figures and complicates any usd forecast for investors tracking the segment.
North america and the united states are only starting to confront this classification debate. Early capsule hotels in cities like New York or San Francisco often navigated existing hotel rules by treating pods as compact rooms, while others leaned on hostel regulations to justify higher bed density, and both approaches left regulators playing catch up. As more business travelers and design minded solo guests embrace capsules as a legitimate hotel alternative, pressure will grow for a dedicated capsule hotel category that recognises their specific type, traveler type and booking mode patterns.
Operators themselves have a strategic choice to make in this evolving global market. Some still prefer to hide inside existing hostel or hotel labels to avoid new scrutiny, but that short term tactic risks long term constraints on market share, market size and product innovation. A clearer capsule hotel classification regulation framework would allow premium capsule hotels to position themselves transparently in the hotel market, attract the right traveler type age segments and participate fully in sustainability programmes such as those highlighted in the report on eco certified capsule stays.
For travelers, the benefit of a distinct capsule hotel category is straightforward. When capsule hotels are recognised as a separate type within the hotels market, booking platforms can present clearer filters, regulators can enforce pod specific safety standards and analysts can produce more accurate global market analysis that reflects real market growth rather than blurred data. As capsules spread from asia pacific to latin america, north america, the middle east and east africa, the debate over hotel, hostel or new category will decide not only how the segment is taxed and zoned, but also how confidently travelers can choose a capsule hotel for their next business or leisure stay.
Key figures shaping capsule hotel regulation and market dynamics
- Japan’s Fire Service Act and Building Standards Act were adapted to accommodate capsule hotels as a distinct hotel type, which has enabled steady domestic market growth and made Japan the reference point for capsule hotel classification regulation in asia.
- Industry reports on the global market for capsule hotels indicate that asia pacific currently holds the largest regional market share, with strong pipelines in cities such as Tokyo, Osaka, Seoul and Singapore, while north america and europe show faster relative growth from a smaller base.
- Analysts tracking the wider hotel market note that compact formats, including capsule hotels and micro hotels, are gaining share among younger traveler type age groups, especially solo and business travelers who prioritise location and design over room size.
- Comparative studies of hotels market regulations show that countries which create a clear legal category for capsule hotels tend to see higher investment, more consistent safety standards and better quality control than countries that force capsules into generic hotel or hostel rules.
- Urban planning reviews in the united states and europe highlight that zoning decisions about where capsule hotels may operate directly influence their market size and market share, particularly in central business districts and near major transport hubs.